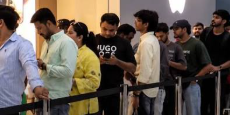
When the iPhone 18 Pro went on sale in India, buyers queued overnight outside Apple stores, though the same phone could be ordered online with delivery in minutes. With roughly 60% of premium smartphones bought on EMI and household debt at 45.5% of GDP, the spectacle raises an uncomfortable question. This article examines buyers who finance a depreciating device to signal status they cannot afford, and why the real cost lies in lost savings, liquidity and financial freedom, not in the price tag itself.
A well-funded purchase of an iPhone 18 Pro, made from genuine surplus income, is a legitimate act of consumption. This article is concerned with a different category of buyer: one who queues overnight, finances the device through a card or a consumer loan, commits to an 18-month repayment schedule, and describes the outcome as a lifestyle choice.
The Launch-Day Spectacle
The iPhone 18 Pro and Pro Max went on sale in India on 18 September, and queues formed outside Apple stores in Delhi, Mumbai, Bengaluru and Noida. Prices begin at Rs 164900 for the Pro and Rs 179900 for the Pro Max. Several customers had been waiting since 10 pm the previous night. The same devices were simultaneously available online, with quick-commerce platforms promising delivery within minutes. The queue conferred no functional advantage. Its only real product was an audience.
Market research data indicates that roughly 60% of premium smartphones in India are purchased on EMI. A separate tracker projects that financing will account for 42% of all smartphone sales in 2026. Apple buyers carry the longest average repayment tenure, at 17.2 months. Zero-cost EMI schemes soften the headline interest burden, but they do not change the underlying economics. A smartphone is a rapidly depreciating asset. A buyer who finances one is servicing a liability whose resale value is eroding faster than the outstanding principal.
The macroeconomic backdrop reinforces the concern. Household debt now stands at 45.5% of GDP, above its five-year average, and non-housing retail loans account for 58.4% of that total. Household savings, meanwhile, remain below pre-pandemic levels. The RBI has repeatedly flagged borrowing for non-productive, depreciating assets as a risk to household balance sheets.
The behavioural drivers are well documented. An IDC analyst observed some years ago that the smartphone in India functions more as a status and style symbol than as a communication device, shaped by peer pressure and the need to appear current. A study of iPhone buyers in Pune, a regional academic study, similarly found that fear of missing out, peer pressure and brand image influenced purchase decisions, often irrespective of need. Retail accounts from Kashmir point the same way: young buyers opting for expensive handsets on EMI despite affordability concerns, frequently with parental consent so that the child is not excluded from the peer group. This is classic conspicuous consumption, in which the device behaves like a Veblen good, valued for what it signals rather than what it does. The distortion arises when the signal is financed by debt. The purchase is made to be seen, while the borrowing is designed to remain invisible.
The Customer as Campaign
Apple's marketing strategy depends on this psychology. The overnight queue, the unboxing videos and the first-day ritual generate organic reach at no cost to the company, with buyers supplying the content. A consumer who borrows to participate becomes an unpaid brand ambassador, while the lender earns the interest on that participation.
Consider a luxury watch worn by an employee whose entry and exit times are fixed and whose job depends on meeting deadlines. The object signals autonomy, but the wearer has little. An EMI operates on the same logic. A salaried buyer who commits future cash flow to a Rs 1.65 lakh handset has ceded a measure of financial flexibility to a lender, and the real cost lies in what that cash flow could otherwise have done: building an emergency corpus, funding a systematic investment plan, or reducing high-interest liabilities. Warren Buffett is often quoted as saying that “if you buy things you do not need, you will soon sell things you need.” For the overstretched buyer, the things that are needed are liquidity, savings and resilience.
On 23 October, the foldable iPhone Duo arrives at Rs 299900, rising to Rs 449900 for the 2 TB variant. Its entry price is more than Rs 1 lakh above the US price. For buyers with genuine surplus, it is a discretionary indulgence. For those planning to stretch the cost across 24 months to remain relevant in the group chat, it is a case study in misallocated capital.
Three questions can separate a prudent purchase from a status-driven one. Can the full amount be paid today without drawing on the emergency fund? Would the purchase still appeal if nobody could see it? Does the monthly instalment sit comfortably within the buyer's income-to-obligation ratio if income or expenses shift? If any answer is negative, the problem is not the phone. It is the price of appearing to afford it.
Shadab Khan is a student pursuing Law from Jamia Millia Islamia.
Disclaimer: The opinions expressed in this publication are those of the author. They do not purport to reflect the opinions or views of The Jamia Review or its members.